Your car payment may be one of the biggest fixed expenses in your monthly budget. When you have a little room to improve it, the question becomes refinance vs paying extra principal: should you seek a better loan, or send more money to the lender you already have?
Both moves can reduce the interest you pay. But they work differently. Refinancing can change your rate, payment, and loan term. Extra principal payments leave your existing loan in place and help you pay down the balance faster. The right choice depends on what you need most right now: monthly breathing room, lower total interest, or a faster path to owning your vehicle free and clear.
Refinance vs Paying Extra Principal: The Key Difference
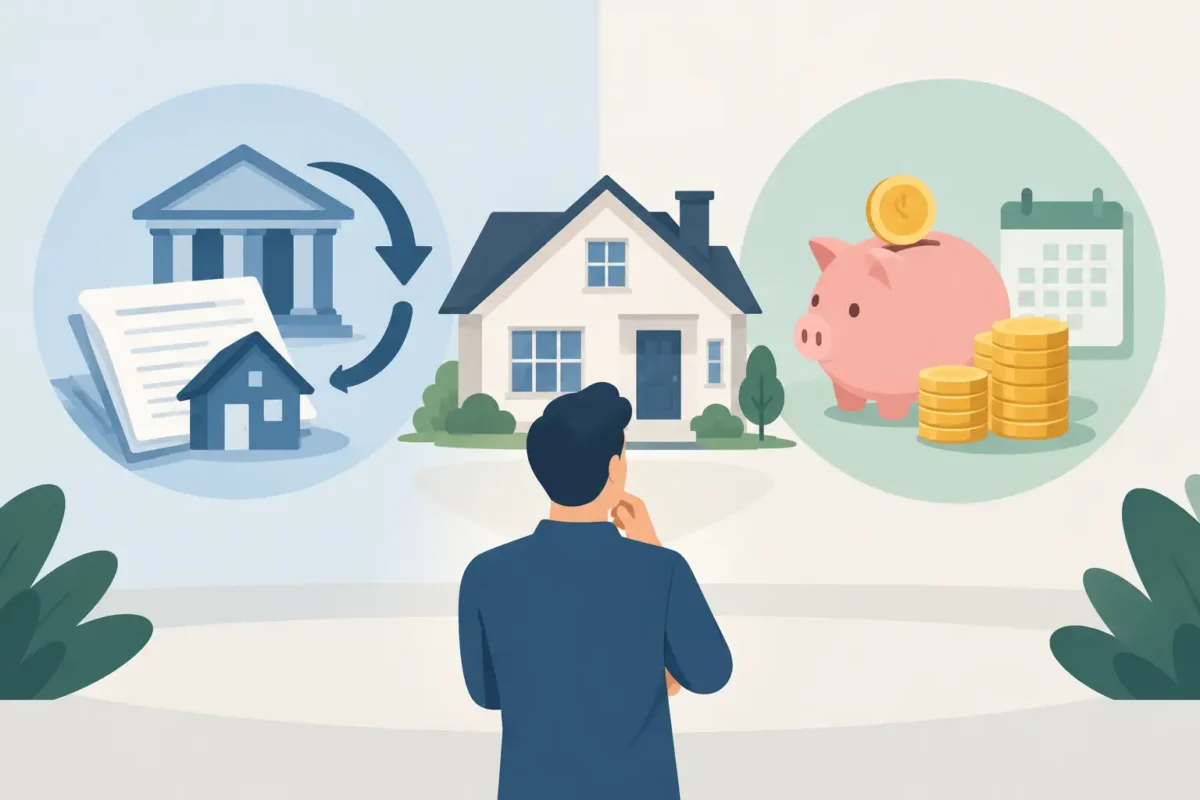
Paying extra principal means adding money beyond your required payment and directing it toward the loan balance. Because interest on an auto loan is generally calculated from the remaining balance, reducing that balance early can reduce future interest charges. You keep the same interest rate and the same loan agreement, but you may finish paying the loan sooner.
Refinancing replaces your current auto loan with a new one. If you qualify for a lower rate, you may reduce interest costs. You can also choose a different repayment term. A longer term may lower the required monthly payment, while a shorter term may help you pay off the vehicle faster, though the monthly payment could rise.
The distinction is simple: extra principal accelerates the loan you have. Refinancing gives you an opportunity to reset the loan terms.
When Paying Extra Principal Can Make Sense
Extra principal is often a strong option when your current interest rate is already competitive and your required payment fits comfortably in your budget. In that situation, there may be little reason to replace the loan. Putting additional money toward principal lets you use available cash to shorten the payoff timeline.
For example, suppose your required payment is $450 and you can reliably afford $500. Applying that extra $50 to principal each month can reduce your balance more quickly. The earlier you do it, the more potential interest savings you may see because there are more future payments left for the lower balance to affect.
This approach also gives you flexibility. If an expensive month comes along, you can generally return to making your required payment. You are not locked into a higher monthly obligation just because you made extra payments in the past.
Before sending extra money, check your loan agreement or contact your lender. Confirm there is no prepayment penalty and ask how extra funds are applied. You want the additional amount credited to principal, not simply treated as an early payment for the next month. Keep records of your payments and review your balance periodically.
Extra principal may be less practical if you have no emergency savings, high-interest credit card debt, or a payment that is already putting pressure on your household budget. It is helpful to pay down a car loan faster, but not if doing so leaves you short on essentials or forces you to rely on more expensive debt later.
When Refinancing Your Auto Loan May Be Better
Refinancing may be worth exploring when your current rate is higher than rates you may qualify for today, your credit profile has improved, or your monthly payment no longer works for your budget. A refinance can be especially useful when the goal is immediate cash-flow relief.
A lower interest rate can reduce the cost of borrowing. If you select a longer term, the payment may drop further because the remaining balance is spread across more months. That can free up money for groceries, insurance, savings, or other priorities. The trade-off is that extending repayment can increase total interest over the life of the loan, even with a lower rate.
That does not mean a longer term is automatically a bad move. A lower required payment can create valuable flexibility during a tight financial period. If your new loan has no prepayment penalty, you may be able to make extra principal payments when your budget allows. This strategy can give you a lower minimum payment without preventing you from paying ahead in stronger months.
Refinancing can also make sense if you want to move from an unfavorable loan structure to terms that better match your plans. Maybe your original financing was arranged at the dealership when you needed a vehicle quickly. Since then, you may have built a stronger payment history, improved your credit, or simply gained a clearer picture of what payment works for your household.
OpenRoad Lending helps eligible vehicle owners explore refinance options through a streamlined online process, so you can review a no-obligation quote before deciding whether a new loan makes financial sense.
Compare More Than the Monthly Payment
A lower payment gets attention because you feel the difference right away. Still, it should not be the only number you compare. Review the new interest rate, the number of months left on the loan, the total amount financed, and the estimated total of payments.
Imagine you owe $18,000 on your current auto loan. Refinancing into a lower rate could reduce your payment and interest expense. But if the new term starts over for many more months, the lower payment alone may not tell the whole story. Look at how long you will be making payments and what the loan could cost if you only make the required amount.
Also compare the refinance offer with what would happen if you kept your current loan and made extra principal payments. If your existing rate is low and you can comfortably pay more each month, keeping the loan may produce a faster payoff without the need for a new application. If the payment is too high or the rate is costly, refinancing may offer the more meaningful improvement.
A Simple Way to Make the Decision
Start with your main goal. If reducing the required payment is urgent, refinancing is usually the option to evaluate first. Sending extra principal does not lower your contractual monthly payment, even though it can help you pay off the loan early.
If your payment is manageable and you want to minimize interest while becoming debt-free sooner, extra principal can be a straightforward choice. It works best when you can make consistent additions without draining your cash reserves.
If you want both flexibility and a potentially better rate, consider refinancing first and then making extra payments on the new loan when possible. Just be sure the numbers support the move. A refinance should be judged by its full terms, not only by the payment displayed at the top of the offer.
Your current loan stage matters, too. Extra payments tend to have more impact earlier in repayment, when the balance is higher. Refinancing may also be more compelling earlier if you can meaningfully improve your rate. If you are close to paying off your vehicle, the available savings from either option may be smaller, so compare carefully before taking action.
Questions to Ask Before You Choose
Ask your current lender for your payoff amount, not just the balance shown on your last statement. Then review your current interest rate, remaining term, monthly payment, and any prepayment policy. Those details provide the baseline for every comparison.
For a refinance offer, ask what rate and term you qualify for, whether there are any applicable fees, and how much you would pay over the full term if you made only the required payments. For extra principal, decide on an amount that fits your budget even when costs are higher than usual.
There is no prize for choosing the fastest payoff plan if it creates financial stress. The better choice is the one that supports your budget now while moving your loan in a healthier direction. A lower payment can provide needed relief, and a disciplined extra-payment strategy can shorten the road ahead. Choose the option that lets you keep moving forward with confidence.